18+ only. The +500% promotional headline was confirmed by the site owner on 5 October 2026. Availability depends on your location and eligibility. The bonus structure, maximum amount, qualifying deposits, wagering, eligible games, maximum bets, expiry and cashout limits must be checked in the operator's live terms; they have not been supplied here. No payout time or acceptance in your country is guaranteed. Offshore operator; not licensed to offer online casino services in Australia. Gambling involves financial risk. Checked: 2026-10-05. 18+. Gambling involves financial risk.
18+ only. The +500% promotional headline was confirmed by the site owner on 5 October 2026. Availability depends on your location and eligibility. The bonus structure, maximum amount, qualifying deposits, wagering, eligible games, maximum bets, expiry and cashout limits must be checked in the operator's live terms; they have not been supplied here. No payout time or acceptance in your country is guaranteed. Offshore operator; not licensed to offer online casino services in Australia. Gambling involves financial risk. Checked: 2026-10-05. 18+. Gambling involves financial risk.
Google Pay is not a funding source. It is a wrapper that presents a stored card to a cashier without exposing that card's printed number, which means every question worth asking about a deposit made this way is really a question about the card underneath and the bank that issued it. Two consequences follow, and they run the whole of this page: the credit prohibition sitting over interactive gambling in Australia attaches to the instrument inside the wallet rather than to the wallet, and a wallet that pays in with one tap ordinarily has no return leg for a casino withdrawal. The filter below judges operators on whether the wallet is genuinely selectable from an Australian session and on what they publish about the route a balance takes on the way back out, because with a token-over-card rail those two readings are the same decision taken at two different times.
Updated October 2026 Offshore operators — not licensed in Australia Payout speed stated by operator 18+ only
OnlinePokies, live tables and sport, online
Advertisement · 18+ · Partner link
Play online: pokies, live dealer tables and sport
A venue keeps hours and a dress code, and the floor is a drive away. The same pokies and tables run online at any hour, most games have a demo mode so you can see how one pays before you stake anything, and deposits go through PayID or a bank transfer.
Welcome offer
Live dealer tables
Pokies and crash games
PayID deposits
Plays on a phone
Play hereA commercial partner, not an independent ranking.
18+ · Partner link · Bonus conditions apply
This block is advertising: if you open an account from the button, this site is paid a commission. No online casino holds an Australian licence, so an Australian regulator will not take a complaint about one and BetStop does not cover it. Check the wagering requirement, the time limit and the withdrawal rules before you deposit. Over 18 only. Gambling can become a problem: Gambling Help Online, 1800 858 858, is free and open at any hour.
Banking · 2 named options
Operator comparison for this category
The shortlist is limited to this site’s commercial partners. Their placement is sponsored; neither is certified as a match for every requirement in this category.
For google pay casinos, the deciding evidence is google pay shown for the device and card. Next compare issuer restrictions and cashout method. Reject any listing that only repeats a welcome-bonus percentage without answering that question.
✓ Google Pay shown for the device and card✓ Issuer restrictions and cashout method✓ Location eligibility and operator identity✓ Current terms and a documented support route
Category status: not independently confirmed for either advertiser. Their general bonus headline does not establish the payment method, game, payout speed or eligibility discussed here.
Sources & comparison basis · reviewed 6 October 2026
Supplier and provider information describes the product, not guaranteed casino availability. Editorial order is not a tested performance score. Promotions remain commercial placements.
The filter this page applies, and what a pass actually proves
A wallet shortlist is only worth reading if it says what was measured, because the measurement everybody takes is close to worthless. A wallet logo in a cashier is a configuration setting and an image file; both survive long after the integration behind them stops completing for Australian accounts. So the filter here is two-sided on purpose. An operator qualifies by presenting the wallet as a live, selectable deposit option to an account registered from Australia, and by publishing, before any money is asked for, a specific named instrument and a specific set of conditions for a balance leaving again by a route the wallet itself does not provide.
That second half is what separates this from a payments badge strip. With a rail that returns money, a depositor can defer the exit question, because the way in has already demonstrated a way out. A wallet token is not that. It carries value into an account across a card network and then stops being relevant, because the account's payout list is built from instruments rather than from wallets, and the instrument that eventually pays you has to exist, be available to an Australian account, and be in your own name. None of that is established by the deposit succeeding.
Where this subject turns up on the two sponsored brands carried on this site, Safe Casino and WinCrown, it turns up on the cashier and banking screens rather than anywhere in the game lobby, which is a note about where to look if you are checking either of them yourself rather than a claim about what either currently lists or a suggestion to fund an account this way. Placements here are commercial. The criterion is published in full so that you can run it against any operator, including those two, and get the same kind of answer either way.
What a pass does not cover is better stated at the front than buried. It does not cover processing speed, the behaviour of a verification queue, the size or honesty of a bonus cap, how a disputed balance is handled, or whether your particular bank will authorise a particular transaction on a particular night. Those are separate questions resting on separate evidence, and several of them cannot be answered from outside an account at all. The check date above the criterion is the most load-bearing figure on the page: cashier method lists change without notice, without a changelog, and usually without anyone correcting the help-centre article that still describes the old one.
The five conditions an operator had to satisfy
Condition one: the wallet is selectable in the live cashier from an Australian session, not merely depicted in a footer. A logo is artwork. A method named in a help-centre article is documentation, written once and revised rarely. The only evidence that counts is a deposit screen offering the wallet to an Australian-registered account, with an amount field that accepts a figure and a confirmation step that does not fail at a country gate. Plenty of payment integrations are published globally and disabled per jurisdiction at the point of use, which is precisely the failure a logo cannot warn you about.
Condition two: the wallet appears as its own entry rather than only as an implied path behind a generic card form. This matters more than it sounds. If the cashier lists the wallet by name, the operator has integrated something that expects a token and the tap flow will run. If the cashier shows only a card form and the wallet merely offers to autofill the stored number into it, the transaction is an ordinary card-not-present payment with a wallet-shaped convenience layer on top, and every property people associate with tokenisation is absent from it. Both can work. They are not the same thing, and the shortlist records which is which.
Condition three: a payout route is named and conditioned in the operator's own published terms before a deposit is required. Named means a specific instrument, not the phrase about various methods being available. Conditioned means the minimum withdrawal, the stated processing window, and whether that window counts weekends can be read by somebody who has not yet registered. This condition decides the list more often than any other, because a wallet deposit makes the exit the only genuinely consequential part of the transaction and a great many operators describe the exit in a sentence that commits to nothing at all.
Condition four: the headline promotion stays open to a deposit funded this way. Excluded-payment-method clauses are ordinary across this market, almost never surfaced on the banner, and usually two clicks underneath it. A promotion is worth nothing to a wallet depositor whose funding route sits on the exclusion list, and support cannot retrospectively make an excluded deposit qualify. This condition tests eligibility only; whether a promotion's own conditions are reasonable is a different judgement, handled in its own section below.
Condition five: the cashier states the deposit minimum, any maximum, and any fee on the screen where you confirm, rather than in a document you would have to go looking for. Two things deliberately did not disqualify an operator. The absence of a payout back to the wallet did not, because that is a property of this class of instrument rather than a deficiency of any operator, and requiring it would produce an empty list that told you nothing. Nor did a disclosed fee: a figure shown before you confirm is a price, while a figure discovered afterwards is a different complaint entirely, and keeping that distinction clean matters.
The five conditions an operator had to satisfy
What one tap actually hands the cashier, screen by screen
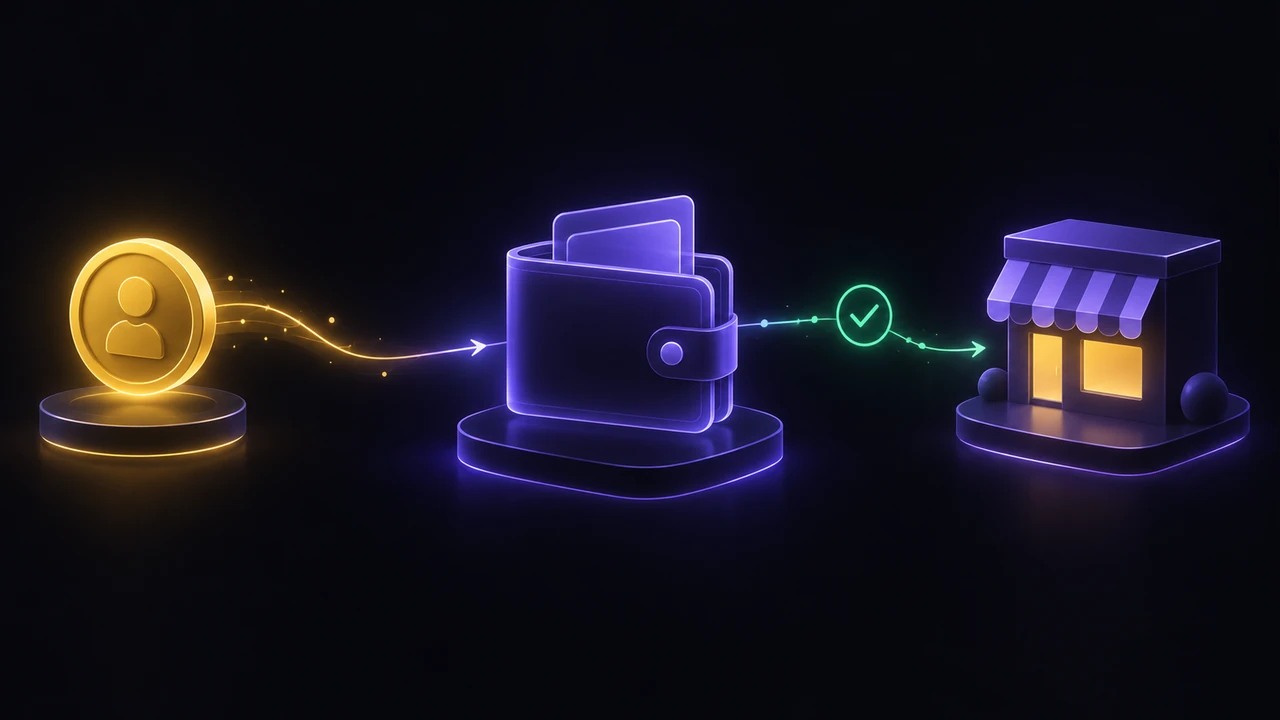
The useful mental model is a relay rather than a payment. You authorise the wallet on your device; the wallet presents a credential that stands in for the stored card rather than the card's own printed number; the operator's payment processor submits that to the card network; the issuing bank decides. The casino is at the end of this chain, not at the start of it, and the party with the final say is your bank. That is why a wallet deposit can fail at an operator that genuinely supports the wallet, and succeed at one whose integration is cruder, with no contradiction between the two outcomes.
Two practical properties fall out of the substitution, and both are worth knowing without overstating. The first is that the operator's own records of the transaction do not contain your card's printed number, which narrows what a breach at the operator could expose. The second is that this narrows nothing at all about the operator holding your identity documents, your address, your balance and your transaction history, all of which it collects anyway. A tokenised deposit is a statement about one field in one database. It is not a privacy posture, and anybody selling it as one is selling something else.
The third property is the one that gets missed: a token is tied to a device and a wallet rather than to you in the abstract. Change phone, remove the card, or let the stored credential lapse, and the funding path you used last month is simply gone, while the casino account and its balance carry on. That matters most for people who fund an account on one device and expect to resolve a withdrawal problem from another, because the deposit history will reference a credential that no longer exists anywhere you can reach.
How a card network actually settles a token, what the stages of a withdrawal are once one is requested, and which instrument classes support a return leg at all are payment-rail questions and belong to pokiescashout.com (payments, withdrawals, KYC, bonus-term arithmetic), which is where this network keeps that detail. What stays on this page is the operator consequence: because the rail hands the decision to your bank and keeps nothing on the way back, the quality of what an operator publishes about its exit is the whole of what you are choosing between.
The credit prohibition, and which card is sitting in the wallet
This is the part most pages on the query get wrong, and the error is always the same shape: treating the wallet as the instrument. A prohibition on funding gambling with credit attaches to the credit facility, not to the software presenting it. A wallet can hold a debit card, a credit card, a prepaid card or several at once, and whichever one is selected at the moment of the tap is the instrument that actually funds the transaction. Reading a wallet as a way around anything misreads the chain described in the previous section, where the wallet is a relay and the issuer decides.
The scope of Australia's prohibition on credit for interactive gambling, who it binds, and what obligations it places on which kind of provider are matters for the legislation itself and for ACMA's published guidance. This page does not paraphrase either into a rule of thumb, because the useful version of that answer is the current one and we are not the authoritative source for it. What this page can say without hedging is the thing a depositor can act on: look at which card the wallet has selected before you confirm, because that is the only question in this area you personally control.
There is a second misreading worth killing in the same breath. A prohibition framed around credit has nothing to say about the legality of the underlying service, and a debit-funded deposit does not make an offshore casino service a lawfully provided one. ACMA's position is that online casino services cannot lawfully be provided to people in Australia. Every operator referred to on this page is offshore. The funding instrument changes which rules apply to the payment; it changes nothing about the standing of the operator receiving it.
The reason this bears on operator choice rather than only on card choice is the decline pattern it produces. An operator whose processor routes wallet transactions in a way that your issuer reads as gambling will see consistent refusals from some Australian banks regardless of which card is in your wallet, and an operator whose routing produces an ambiguous descriptor may be approved by the same bank on the same day. That difference is invisible from the outside, undocumented by anybody, and it is the single most common reason a cashier that genuinely supports the wallet still does not work for you.
A note on what to do when a deposit is declined, since the instinct is uniformly wrong. The instinct is to retry, then to try another card, then to call the bank and ask for the block to be lifted. A decline that originates with your issuer is the system working as designed, and talking a bank into reversing it is not a payment problem being solved. Nothing on this page is advice on getting around a card block, a bank control or a statutory prohibition, and an operator offering to help with any of those has told you something about itself worth writing down.
Terms and limits are published by the operator and change without notice. Read the live page before acting on anything here.
Where a wallet deposit actually fails, and how to read the error
Four parties can refuse a wallet deposit and they produce errors that look alike on screen. The operator can refuse at the country gate, before the wallet sheet even opens, which usually presents as the method vanishing from the list or an immediate unavailability message. The processor can refuse, which often produces a generic failure with no explanation. The card network can refuse on routing grounds. And your issuer can decline, which is the most common outcome and the one most often misattributed to the casino.
Telling them apart is mostly a matter of where the failure happens. If the wallet sheet never opens, the problem is upstream of your bank and nothing you do on the phone will change it. If the sheet opens, you authorise with a fingerprint or a face scan, and the failure arrives after that, the transaction reached the networks and was refused somewhere past the wallet. If your banking app shows an attempted or declined transaction, the issuer saw it and said no. That last case is the only one where the decision was ever yours to ask about, and it is the one case where asking is pointless.
An operator's conduct around a failure is a genuine signal about the operator, and it costs nothing to observe. Does the cashier say which stage failed, or does it return one message for every possible cause? Does live chat distinguish between its own gate, its processor and your bank, or does it answer every decline by recommending a different method? Does it suggest a route that conspicuously sidesteps whatever just blocked the transaction? A support desk that reaches immediately for a workaround has answered a question you did not ask.
There is one failure mode specific to this rail that deserves naming because it is expensive. A declined transaction can still place an authorisation hold against the card, and a hold is not a payment but it is also not instantly reversed. A depositor who retries four times in five minutes and then switches cards can end up with several holds outstanding and no balance at the casino. The arithmetic section below works that through. The short version: if a wallet deposit fails twice, stop, check the banking app, and do not keep tapping.
Where a wallet deposit actually fails, and how to read the error
Why the balance does not come home through the wallet
Treat the wallet as inward only unless the operator's own banking page says otherwise in writing. Casino payout lists are built from instruments that can receive a credit in a named person's name, and a device-bound token presenting a stored card is not ordinarily one of those. In practice the exit is a card credit back to the underlying card, or a bank transfer, or some instrument entirely unconnected with how you paid in, and which of those applies to an Australian account is a question for the banking page rather than an inference from the deposit having worked.
That produces the decision rule the whole page is built around. Judge the operator on its exit terms first, then confirm the wallet is selectable, rather than the reverse. The habit most depositors bring to a cashier is to find the method already in their hand, fund the account, and deal with the rest later. On a rail with no return leg that sequence puts the irreversible step first and the research second, which is exactly backwards, since the only thing research can still change is whether to proceed at all.
The name-matching clause is the specific sentence to hunt for, and it is where wallet depositors most often come unstuck. A tap requires no account in anybody's name at the point of deposit; a payout does, and operators routinely require the receiving instrument to belong to the account holder and refuse third-party transactions in both directions. Fund an account from a wallet holding a card that is not yours, or one on a shared family arrangement, and the account has been funded by one party and is payable only to another. That is not a trap so much as an obvious consequence of the asymmetry, met at the worst possible moment.
Verification lands at the same moment and for the same reason. A wallet deposit defers identity checks rather than removing them, because the balance has to leave by an instrument that belongs to somebody by name, and operators ordinarily verify the account holder at that point rather than at the deposit screen. The documents, formats and queue behaviour are covered on pokiescashout.com; the question this page can answer in advance is narrower and worth asking: does the operator publish its verification requirements where a prospective customer can read them, or do they appear only once a withdrawal has been requested?
Two pieces of wording deserve scepticism when you find them on a banking page. A processing window stated without a stage breakdown is a single figure that may describe the operator's internal review, or the receiving instrument's settlement, or an optimistic sum of the two, and it cannot be held to anything because it never said which. A clause reserving the right to request further documentation at any time is ordinary rather than sinister, but it makes the stated window a target rather than a commitment. Neither is a reason to walk away; both are reasons to size a balance conservatively.
Floors, holds and retries: the arithmetic on the cashier screen
Three figures govern a wallet deposit and all three are published rather than estimated. The cashier's stated minimum, its stated maximum, and any fee shown on the confirmation screen. Read all three before the sheet opens, because a wallet tap compresses the moment of commitment into a fingerprint and there is no second screen on which to notice a fee. We publish no operator's figures here: those change without notice and the authoritative version is the live cashier page under your own session.
The decision runs backwards from the exit, not forwards from the wallet. Take the published minimum withdrawal from the banking page, then set the deposit against it. Worked through with illustrative figures rather than any operator's actual ones: if the minimum withdrawal is A$50 and you intend to deposit A$20, then any balance below A$50 cannot leave the account, and its only available use is to be staked again. That is not a hazard peculiar to obscure operators. It is a structural consequence of a withdrawal floor sitting above a small deposit, and it is legible in the terms before anything moves.
Now the retry arithmetic, which is the one piece of this page that costs real money if it is ignored. Suppose a A$30 deposit is declined by your issuer and the attempt places an authorisation hold. Four taps in quick succession can leave four holds of A$30 against the available balance on the card — A$120 of headroom gone — with nothing credited at the casino, because a hold is not a payment and not an instant reversal either. Add a second card and the pattern repeats on that one. The rule that falls out is simple: two failures, then stop and open the banking app.
One more piece of arithmetic applies if the operator's cashier charges in a currency other than Australian dollars. A conversion applied by the card network or the issuer sits on top of anything the cashier displays, which means the figure on the confirmation sheet is not necessarily the figure on the statement, and a withdrawal converted back can land on a different rate again. We do not publish rates, margins or fees for any operator or any issuer. Our AUD casinos shortlist filters operators on whether the account is actually denominated in Australian dollars, which is the single check that removes this whole class of arithmetic.
Excluded-payment-method clauses and the wallet deposit
A promotion's terms document is where a wallet deposit most often quietly loses its value, and the clause responsible is short enough to miss. It lists which funding routes qualify for the offer, and wallet methods are a common omission — sometimes named directly, sometimes caught by a broader exclusion covering e-wallets or prepaid instruments. The clause is ordinarily not on the banner, not in the registration flow and not in the cashier. It is in the promotional terms under a heading about eligibility or qualifying deposits, and searching that document for exclude, qualifying and wallet finds it in under a minute.
Beyond eligibility, four more figures in the same document decide whether an offer is worth anything: the turnover requirement and what it applies to, the maximum stake permitted while bonus funds are live, the expiry period, and any ceiling on what may be withdrawn from bonus winnings. A percentage on a banner tells you nothing about any of them. This site publishes no turnover multiples, caps or expiry periods for any brand, because those are operator figures that change without notice and the authoritative version is the live terms page on the operator's own site.
Turning those four figures into an expected cost — what a multiple applied to deposit-plus-bonus demands in total stakes, how a maximum-stake rule interacts with the time left before expiry — is bonus-term arithmetic and lives on pokiescashout.com (payments, withdrawals, KYC, bonus-term arithmetic). The operator-selection consequence is what belongs here: an offer whose conditions you cannot locate is an offer you cannot price, and an operator that publishes them plainly has told you something real about itself before you have risked anything.
Ordering matters and is easy to get wrong, because each check is free at the moment listed and impossible to act on afterwards. Check eligibility before the tap, check the turnover and expiry before the deposit lands, and check the maximum-stake rule before the first spin. Our welcome bonus shortlist and the low-wagering shortlist sort operators on the conditions rather than the headline, which is the same ordering applied to a different question.
The register check on the company, and the Australian legal position
Every operator reachable from Australia for this purpose is offshore, and the only verifiable part of an offshore licence claim is the regulator's own public register. Four minutes is enough for it. Read the registered company name and place of registration from the site footer or the opening definitions of the terms. Type the regulator's own address into the browser yourself rather than clicking the badge. Open its public register, search the company name rather than the trading name, and confirm the exact domain you were sitting on appears against that entry.
A register search comes back three different ways, and conflating them is how a badge keeps working long after it stopped meaning anything. An empty result for the company name means the body named in the footer does not vouch for that company at all, whatever the artwork says. A result listing the company but not the domain you were standing on is the commonest outcome and the most misread, because these registrations are granted to a company for specific named websites: a genuine entry can sit alongside a site it was never extended to cover, and the badge will look identical on both. A result carrying a status of expired, suspended or revoked settles the matter in the other direction, which is why the status field is worth reading after the name matches rather than instead of checking it. No licensing authority and no licence number appears anywhere on this site for any brand it carries — that data is not ours to publish, and a claim we cannot source is not one we will repeat on an operator's behalf.
Treat the badge itself as decoration: an image file, copyable in an afternoon, and a surprising number of them link nowhere or link to a page hosted on the casino's own domain. Our licences explained guide sets out how to read an entry once you have found it, including what the common offshore registrations do and do not require of an operator, and why no Australian authority ever appears on one. A current entry means a company is registered with that body for that domain. It does not mean an Australian consumer protection applies.
ACMA's position is that online casino services cannot lawfully be provided to people in Australia, and that frames everything above. No operator in this market is Australian-authorised, no offshore registration amounts to Australian authorisation, and a page treating offshore as a feature that distinguishes one operator from another would be describing the entire market as though it were a subset of it. The practical consequence is the shape of the escalation path, which is short: the operator first, in writing, through its published complaints process, quoting the clause at issue with dated evidence; then the offshore licensor named in the footer, if a register confirmed one exists. That is the end of it.
Domain blocking is routinely misread as an operator disappearing, and it is worth understanding before it happens rather than after. When a domain stops resolving from an Australian connection, the company still exists and still owes whatever it owed; what has broken is your route to the account and to support. Our ACMA blocked sites page covers what that does to an existing account. Mirror domains follow from blocking and need care, because the channel a replacement address arrives through is the only thing separating it from a phishing clone: announced inside your logged-in account or from the company's own email domain is plausible, while a search advertisement or a message from a stranger is how wallet credentials and card details get harvested.
Pokies are 18+ and gambling involves financial risk. A wallet tap is the lowest-friction deposit instrument there is, which is a real property of the method rather than of any operator: the gap between deciding and committing is a fingerprint wide, and the spend is spread across a card statement rather than totalled anywhere you will look. If that frictionlessness is the appeal, it is also the thing to be honest about. Free, confidential support is available 24/7 on 1800 858 858.
Google Pay against the other ways into an Australian cashier
Comparing rails is only useful as an operator-selection exercise, so that is the frame. Four questions separate the options for somebody deciding where to hold an account: does the rail return money, does it depend on a bank or card issuer approving a gambling transaction, does it require an instrument in your own name at the point of deposit, and does the operator's promotion treat it as a qualifying deposit. Answer those four for each candidate and the operator choice usually narrows before the method choice does.
A wallet token over a card answers no, yes, effectively yes, and sometimes. It returns nothing, it hands the decision to your issuer, the stored card is ordinarily yours, and its promotional eligibility must be read in the terms every time. The other large wallet in this category sits in nearly the same position on all four, and the honest comparison between two wallet rails is not about the wallets at all but about which the operator you already chose on its exit terms happens to list — our Apple Pay shortlist runs the same two-sided filter for that one, and where the two shortlists disagree about an operator the disagreement is cashier configuration rather than a judgement.
A bank rail such as PayID answers yes, differently, yes, and usually: the route exists in both directions, which collapses the exit question into the entry question, at the cost of associating the transaction with an account in your name and of a bank that may still decline it. A cash voucher answers no, no, no, and sometimes: nothing in your name to pay in, nothing returned, and no issuer in the loop at all. Our PayID shortlist and the Paysafecard shortlist apply the same criterion to each, and the three pages together are a map of the trade-offs rather than three recommendations.
Game selection does not belong in this comparison, and the reason is worth stating since cashier pages routinely blur it. Which titles a lobby carries, how volatility behaves, and what a game's designed return is are questions about the games rather than about the operator or the rail, and they are covered on pokiesalmanac.com (game mechanics, RTP, volatility). No deposit method changes a game's designed return, and nothing on this page is a strategy or a way to improve an outcome.
Where this page is weak, stated plainly
The evidence is documentary throughout. Every condition in the criterion was established by reading a cashier screen, a banking page and a terms document — not by funding an account, winning, requesting a withdrawal and watching money arrive. So the page can say a route is offered, conditioned and eligible. It cannot say it completed on a particular night for a particular account, and wallet deposits fail for mundane, invisible reasons — issuer rules, processor routing, a stale stored credential — that no documentary check catches.
No dispute has been tested, because testing one requires having one. The escalation path described above is the path as published. How long it takes in practice, how an operator argues a voided balance, and whether an offshore licensor answers correspondence are the three things a depositor would most want to know and the three this page cannot establish. Treating a published complaints process as evidence that complaints are handled well is exactly the inference this site exists to avoid.
Figures are deliberately absent where a competitor page would print them. No deposit floors, no processing times, no fee schedules, no conversion margins, no turnover multiples, no bonus caps, no licence numbers, no review scores, and no statement of which Australian banks decline which transactions. Each varies by operator, by issuer or by build, and the authoritative version lives on the operator's live cashier and terms pages or with your own bank. Declining to print a number that would be wrong within a month is a house rule rather than an omission.
The population is small, and ordering is not a verdict. A page built from the operators a site carries is not a market survey: plenty of offshore operators list wallet methods and are not covered here. Where this site shows operators in a sequence, that sequence reflects the declared criterion of the page it appears on plus commercial placement — not a payout test, not a safety score. The same operators appear in different orders on different shortlists because each page asks a different question, and a single house ranking reused everywhere would be a sponsorship order wearing a different hat on each page.
Rebuilding the check yourself in ten minutes
Five steps in this order, run against any operator you are considering rather than only those a shortlist carries. The order is the point: each step can make the next unnecessary, and the cheapest refusals come first.
Step one, the exit. Open the banking or withdrawal page before the cashier and read four things: which payout instruments are listed, the minimum withdrawal for the one you would realistically use, the stated processing window, and whether it is expressed in business days. If no instrument available to an Australian account is named, stop here; nothing later in the sequence repairs that. Step two, the rail. Open the cashier and check whether the wallet is listed by name as its own method or merely autofills a card form, then read the minimum, the maximum and any fee displayed on the confirmation screen.
Step three, the clause. Open the promotion terms and search the document for exclude, qualifying, wallet and maximum. The first three find the eligibility clause; the last surfaces the stake rule and any ceiling on bonus winnings in the same pass. Step four, the register. Read the registered company name out of the footer or the opening definitions of the terms, reach the named regulator by typing its address in rather than following the badge, search on that company name instead of the brand you know it by, then read two fields on whatever entry returns — that your exact domain is listed against it, and that the status on it is current.
Step five, the card and the arithmetic. Before the sheet opens, check which card the wallet has selected, and set the deposit by working backwards from the minimum withdrawal read in step one rather than forwards from what is convenient to tap. If a deposit is declined, read where it failed rather than retrying: two attempts, then the banking app. Four screens, ten minutes, and the result is current on the day you look rather than the day a page was published. Keep dated screenshots of the terms you relied on, because documents in this market change without notice or versioning and a screenshot is frequently the only surviving copy of the agreement you need to quote. Pokies are 18+, gambling involves financial risk, and free confidential support is available 24/7 on 1800 858 858.
The filter this page applies, and what a pass actually proves — at a glance
Questions people actually ask
Which casinos accept Google Pay in Australia?
This page does not publish a brand list, because a cashier method list is configuration that changes without notice and a list dated last month is worse than no list. It publishes the filter instead: the wallet selectable and completing from an Australian session, listed as its own method rather than autofilling a card form, a payout instrument named and conditioned in the published terms before you deposit, the headline promotion still open to a deposit funded this way, and the floor, ceiling and any fee shown on the confirmation screen. Run those checks on any operator and the answer is current on the day you look. Every operator in this market is offshore.
Can I withdraw to Google Pay?
Treat the rail as inward only unless the operator's banking page says otherwise in writing. Payout lists are built from instruments that can receive a credit in a named person's name, and a device-bound token presenting a stored card is not ordinarily one of those. In practice a balance leaves by a card credit, a bank transfer or some instrument unconnected with how you paid in, and which applies to an Australian account is a question for the banking page rather than an inference from the deposit having worked. The criterion here deliberately does not require a return leg, because requiring it would produce an empty list.
Does paying through a wallet get around the credit card rules?
No, and the question misreads the instrument. A wallet is a relay that presents a stored card; a prohibition on funding gambling with credit attaches to the credit facility, not to the software presenting it. Whichever card the wallet has selected at the moment of the tap is what actually funds the transaction. The scope of Australia's prohibition on credit for interactive gambling is a matter for the legislation and ACMA's published guidance rather than for a page like this one, and nothing here is advice on getting around a card block, a bank control or a statutory rule.
Why was my Google Pay deposit declined at a casino that lists it?
Four parties can refuse and the errors look alike. If the wallet sheet never opens, the operator's country gate or its processor refused and your bank was never involved. If the sheet opens, you authorise, and the failure arrives after that, it reached the networks. If your banking app shows an attempted or declined transaction, your issuer saw it and said no, which is the most common outcome. Do not retry repeatedly: a declined attempt can still place an authorisation hold, and several holds can consume real headroom on the card with nothing credited at the casino.
Is a wallet deposit more private than typing my card number in?
Narrowly, and only about one thing. The operator's records of the transaction do not contain your card's printed number, which limits what a breach at the operator could expose on that specific field. It changes nothing about the operator holding your identity documents, address, balance and transaction history, all of which it collects anyway, and nothing about the payout being made to an instrument in your own name. A tokenised deposit is a statement about one database field, not a privacy posture.
Will a Google Pay deposit qualify for the welcome bonus?
Sometimes, which is why it is a condition of the filter rather than an assumption. Excluded-payment-method clauses are common, rarely on the banner, and usually two clicks below it — sometimes naming the wallet, sometimes catching it under a broader exclusion for e-wallets or prepaid instruments. Search the promotional terms for exclude, qualifying and wallet before you tap, because support cannot retrospectively make an excluded deposit qualify.
Does a wallet deposit mean I can skip identity verification?
It defers it rather than removing it. A tap requires no identity check, but the balance has to leave by an instrument belonging to somebody by name, and operators ordinarily verify the account holder at that point — later, and with a balance already at stake. The documents and the queue behaviour are covered on pokiescashout.com. What is worth checking in advance is whether the operator publishes its requirements where a prospective customer can read them. Send documents only through the operator's own secure upload inside the account, never as an email attachment to an address handed over in a chat window.
Are these operators licensed to offer online casino services in Australia?
No operator is. ACMA's position is that online casino services cannot lawfully be provided to people in Australia, and every operator referred to here is offshore. This site publishes no licensing authority and no licence number for any brand, because it does not hold that data. Take the company name from the footer, search the named regulator's own public register for that company, and confirm the exact domain appears on the entry with a current status. A current offshore entry is not Australian authorisation and does not bring an Australian consumer protection with it.
18+ only. Gambling involves financial risk and winning is never guaranteed. Online casino services are not licensed in Australia. Free, confidential support: 1800 858 858.